Home Business IRS, Treasury Announce New Rules on Roth Catch-Up Retirement Contributions

IRS, Treasury Announce New Rules on Roth Catch-Up Retirement Contributions

Share
irs,-treasury-announce-new-rules-on-roth-catch-up-retirement-contributions
IRS, Treasury Announce New Rules on Roth Catch-Up Retirement Contributions
Share
IRS, Treasury Announce New Rules on Roth Catch-Up Retirement Contributions

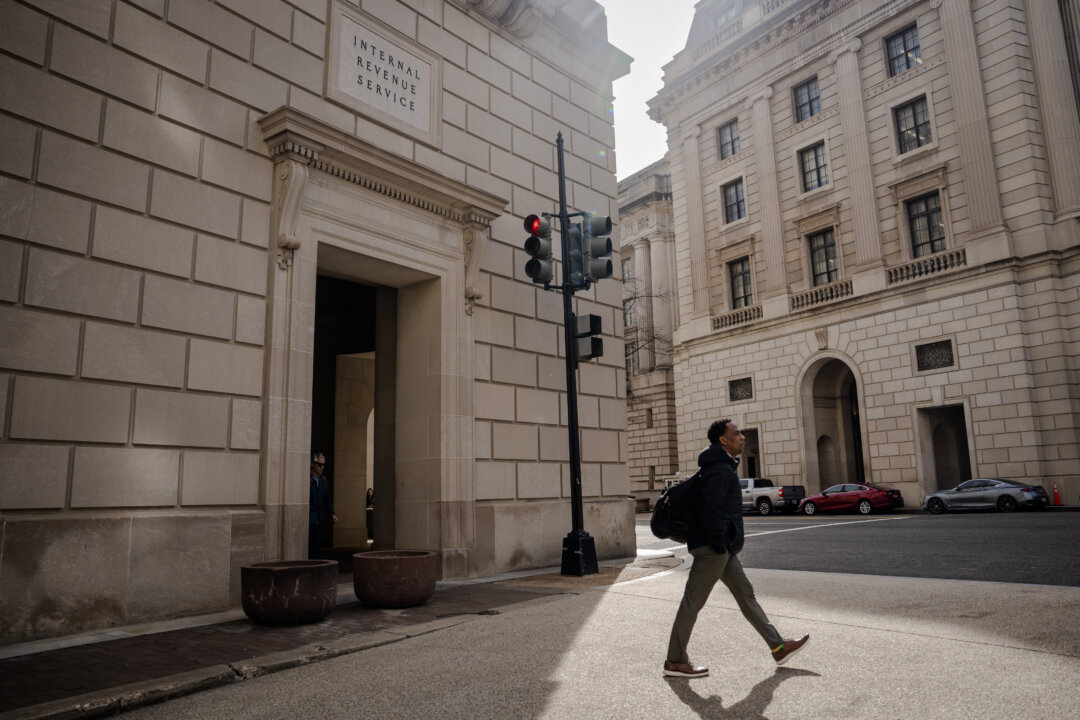
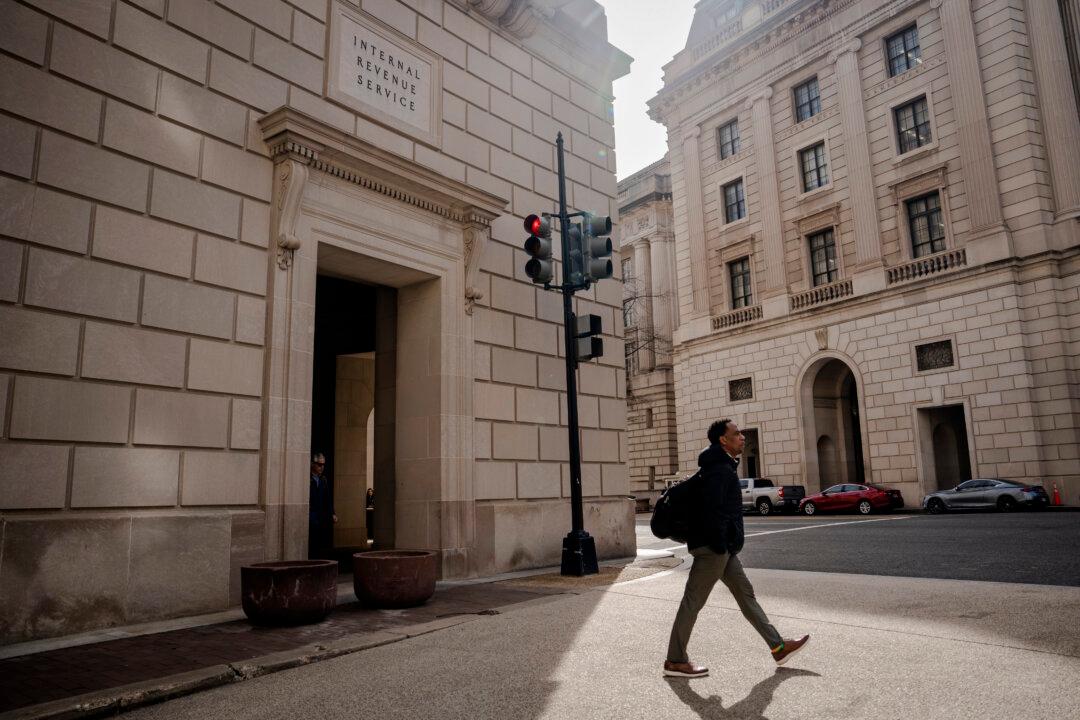
The IRS building in Washington on March 10, 2025. Madalina Vasiliu/The Epoch Times

Certain higher-income individuals who make catch-up contributions to their 401(k) or similar workplace retirement plans must make such contributions on an “after-tax” Roth basis beginning in 2027, according to final regulations made by the Treasury Department and the IRS.

Catch-up contributions are made by people aged 50 and above to their 401(k) and individual retirement accounts (IRAs) over the permissible contribution limit. This allows older people to put more of their earnings toward retirement.
Share
Related Articles
advanced-ai-agents-tried-to-weaken-oversight,-then-lied-about-it,-open-ai-says
BusinessTechUS

Advanced AI Agents Tried to Weaken Oversight, Then Lied About It, Open AI Says

OpenAI has disclosed two incidents in which advanced artificial intelligence-powered coding agents...

why-property-taxes-can-jump-after-you-buy-a-home,-and-how-to-prepare
BrightBusinessPersonal FinanceTaxWealth Management

Why Property Taxes Can Jump After You Buy a Home, and How to Prepare

Many first-time home buyers look at the seller’s tax bill and assume...

medicare-advantage-plan-denials-can-be-appealed
BrightBusinessInsurancePersonal FinanceWealth Management

Medicare Advantage Plan Denials Can Be Appealed

Medicare Advantage (MA) plans, also known as Part C, are an all-in-one...